How can we tell whether a budget variance is temporary or permanent?
Variance timing ambiguitySeparate timing differences from changes in the total expected cost. Reconcile actuals and commitments with the remaining work before choosing a corrective action.
What to do now
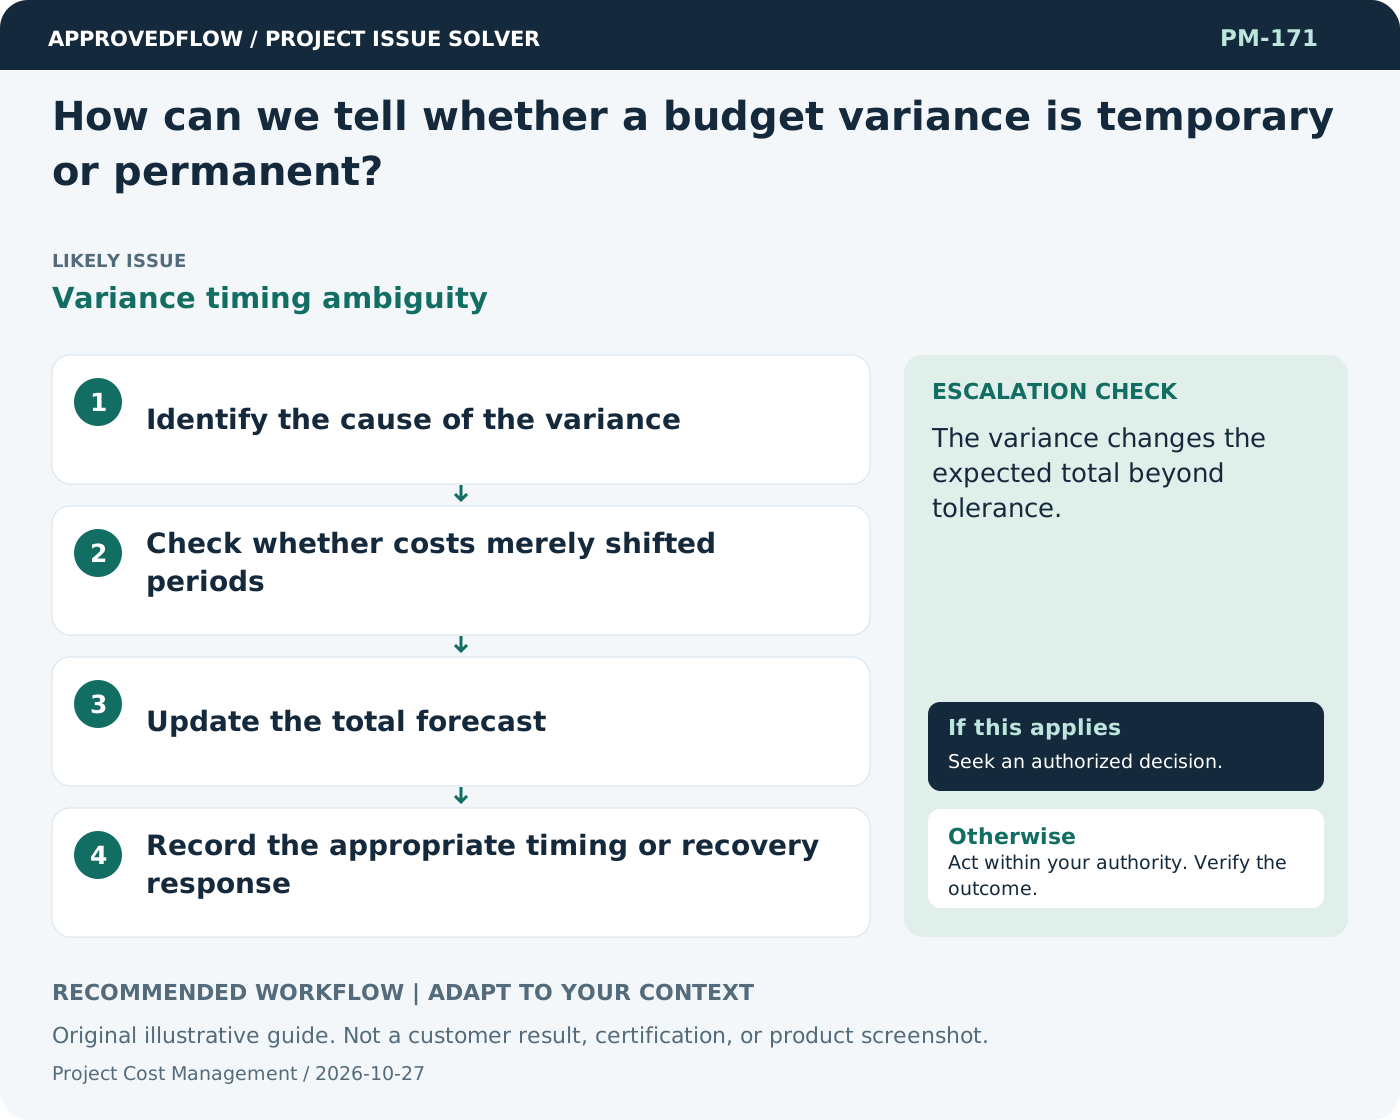
- Identify the cause of the variance
- Check whether costs merely shifted periods
- Update the total forecast
- Record the appropriate timing or recovery response
When to escalate
Escalate when
The variance changes the expected total beyond tolerance.
Who decides
The budget owner and authorized finance representative
Example
A delayed invoice shifts monthly expenditure, while increased specialist rates change the total forecast.
Mistake to avoid
Applying cost-cutting measures to an accounting timing difference.
Prevent a repeat
Review remaining cost and commitments, not only money already spent; reconcile with the authorized finance source.
Related cases
- The project is spending faster than planned. What should I check first?Unexplained cost variance
- A change request has no budget impact listed. Is zero credible?Incomplete change impact
- We have a workaround but no permanent fix. Can we move on?Uncontrolled temporary workaround
- We cannot tell whether this is a project or routine operational work. How should we organize it?Unclear work classification