Our budget ignores internal staff time. Should we include it?
Incomplete cost visibilityTrack internal effort when it affects capacity, business-case comparison, or project economics. Distinguish accounting expenditure from management views of resource consumption and opportunity cost.
What to do now
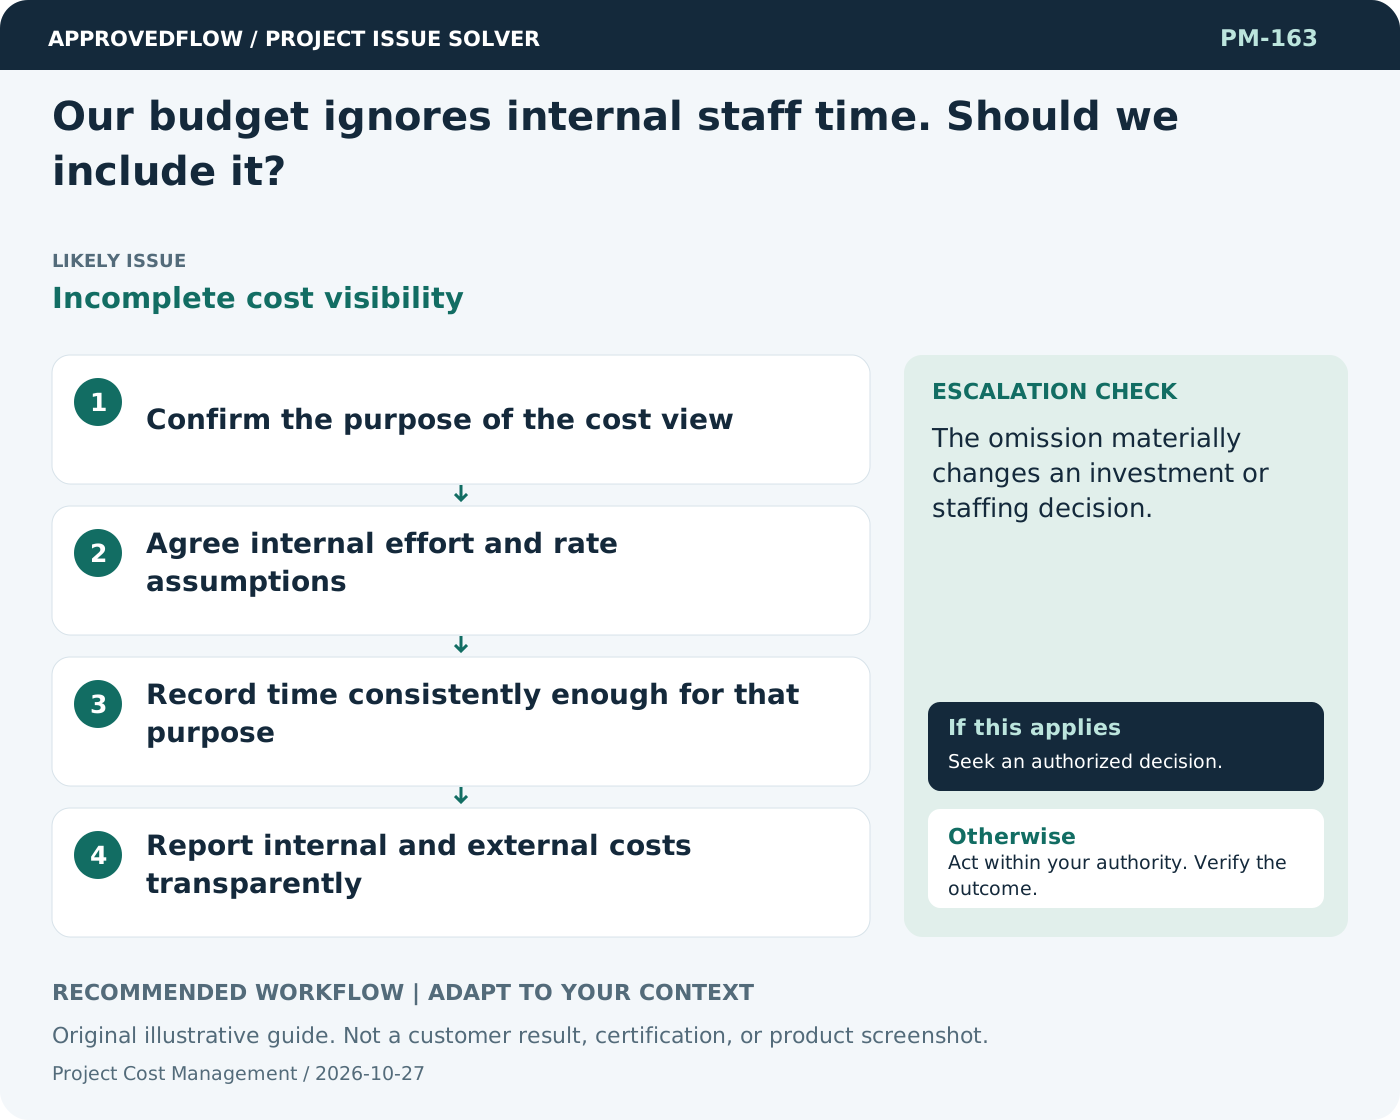
- Confirm the purpose of the cost view
- Agree internal effort and rate assumptions
- Record time consistently enough for that purpose
- Report internal and external costs transparently
When to escalate
Escalate when
The omission materially changes an investment or staffing decision.
Who decides
The budget owner and authorized finance representative
Example
A project comparison includes internal implementation effort while keeping it separate from supplier cash payments.
Mistake to avoid
Treating employees as free because their salaries already exist.
Prevent a repeat
Review remaining cost and commitments, not only money already spent; reconcile with the authorized finance source.
Related cases
- A change request has no budget impact listed. Is zero credible?Incomplete change impact
- How do we forecast the final project cost?Incomplete cost-to-complete forecast
- Our schedule ignores holidays and part-time staff. How do we correct it?Invalid working calendars
- How do we plan for leave without invading privacy?Availability visibility gap