Our business case assumes savings that nobody can explain. Should we accept it?
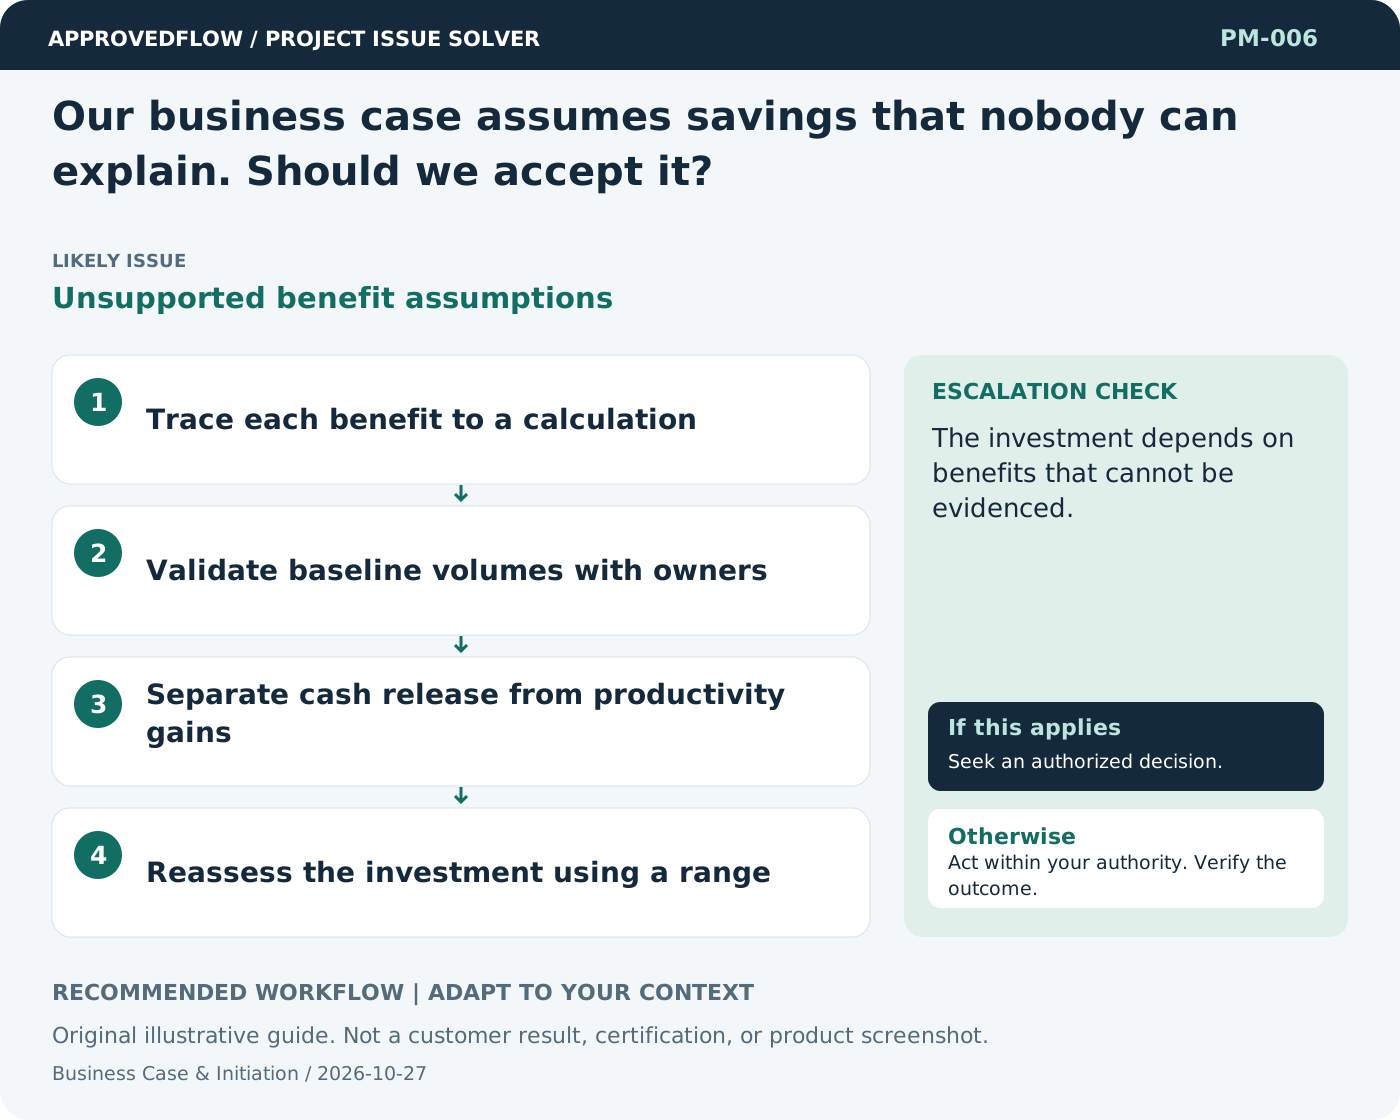
Unsupported benefit assumptionsTreat unexplained savings as assumptions, not established value. Rebuild the estimate from actual volumes, unit costs, adoption assumptions, and the difference between cash savings and released capacity.
What to do now
- Trace each benefit to a calculation
- Validate baseline volumes with owners
- Separate cash release from productivity gains
- Reassess the investment using a range
When to escalate
Escalate when
The investment depends on benefits that cannot be evidenced.
Who decides
The accountable sponsor
Example
An automation proposal distinguishes 300 hours of released capacity from expenditure that will actually disappear.
Mistake to avoid
Counting staff time saved as cash savings without a realizable plan.
Prevent a repeat
At each stage decision, check that the expected outcome, owner and justification remain valid.
Suggested ApprovedFlow setup
- Projects
- Documents
- Approvals
Keep the decision brief with the project and request a recorded sponsor decision before the next commitment. See the platform
Related cases
- The business case is already outdated before kickoff. What should happen?Stale investment rationale
- Nobody knows which assumptions the plan depends on. Where do we begin?Invisible planning assumptions
- The benefit target is unrealistic. How do we revise it?Unsupported outcome target
- Two projects claim the same resource savings. Who reconciles the portfolio?Portfolio benefit overlap